"Once my side hustle matches my salary, I'll quit" is the plan almost everyone starts with, and it's the wrong number by a wide margin. A $65,000 salary and $65,000 of self-employed income are not the same $65,000 — one of them has already had taxes withheld and benefits attached, and the other hasn't.
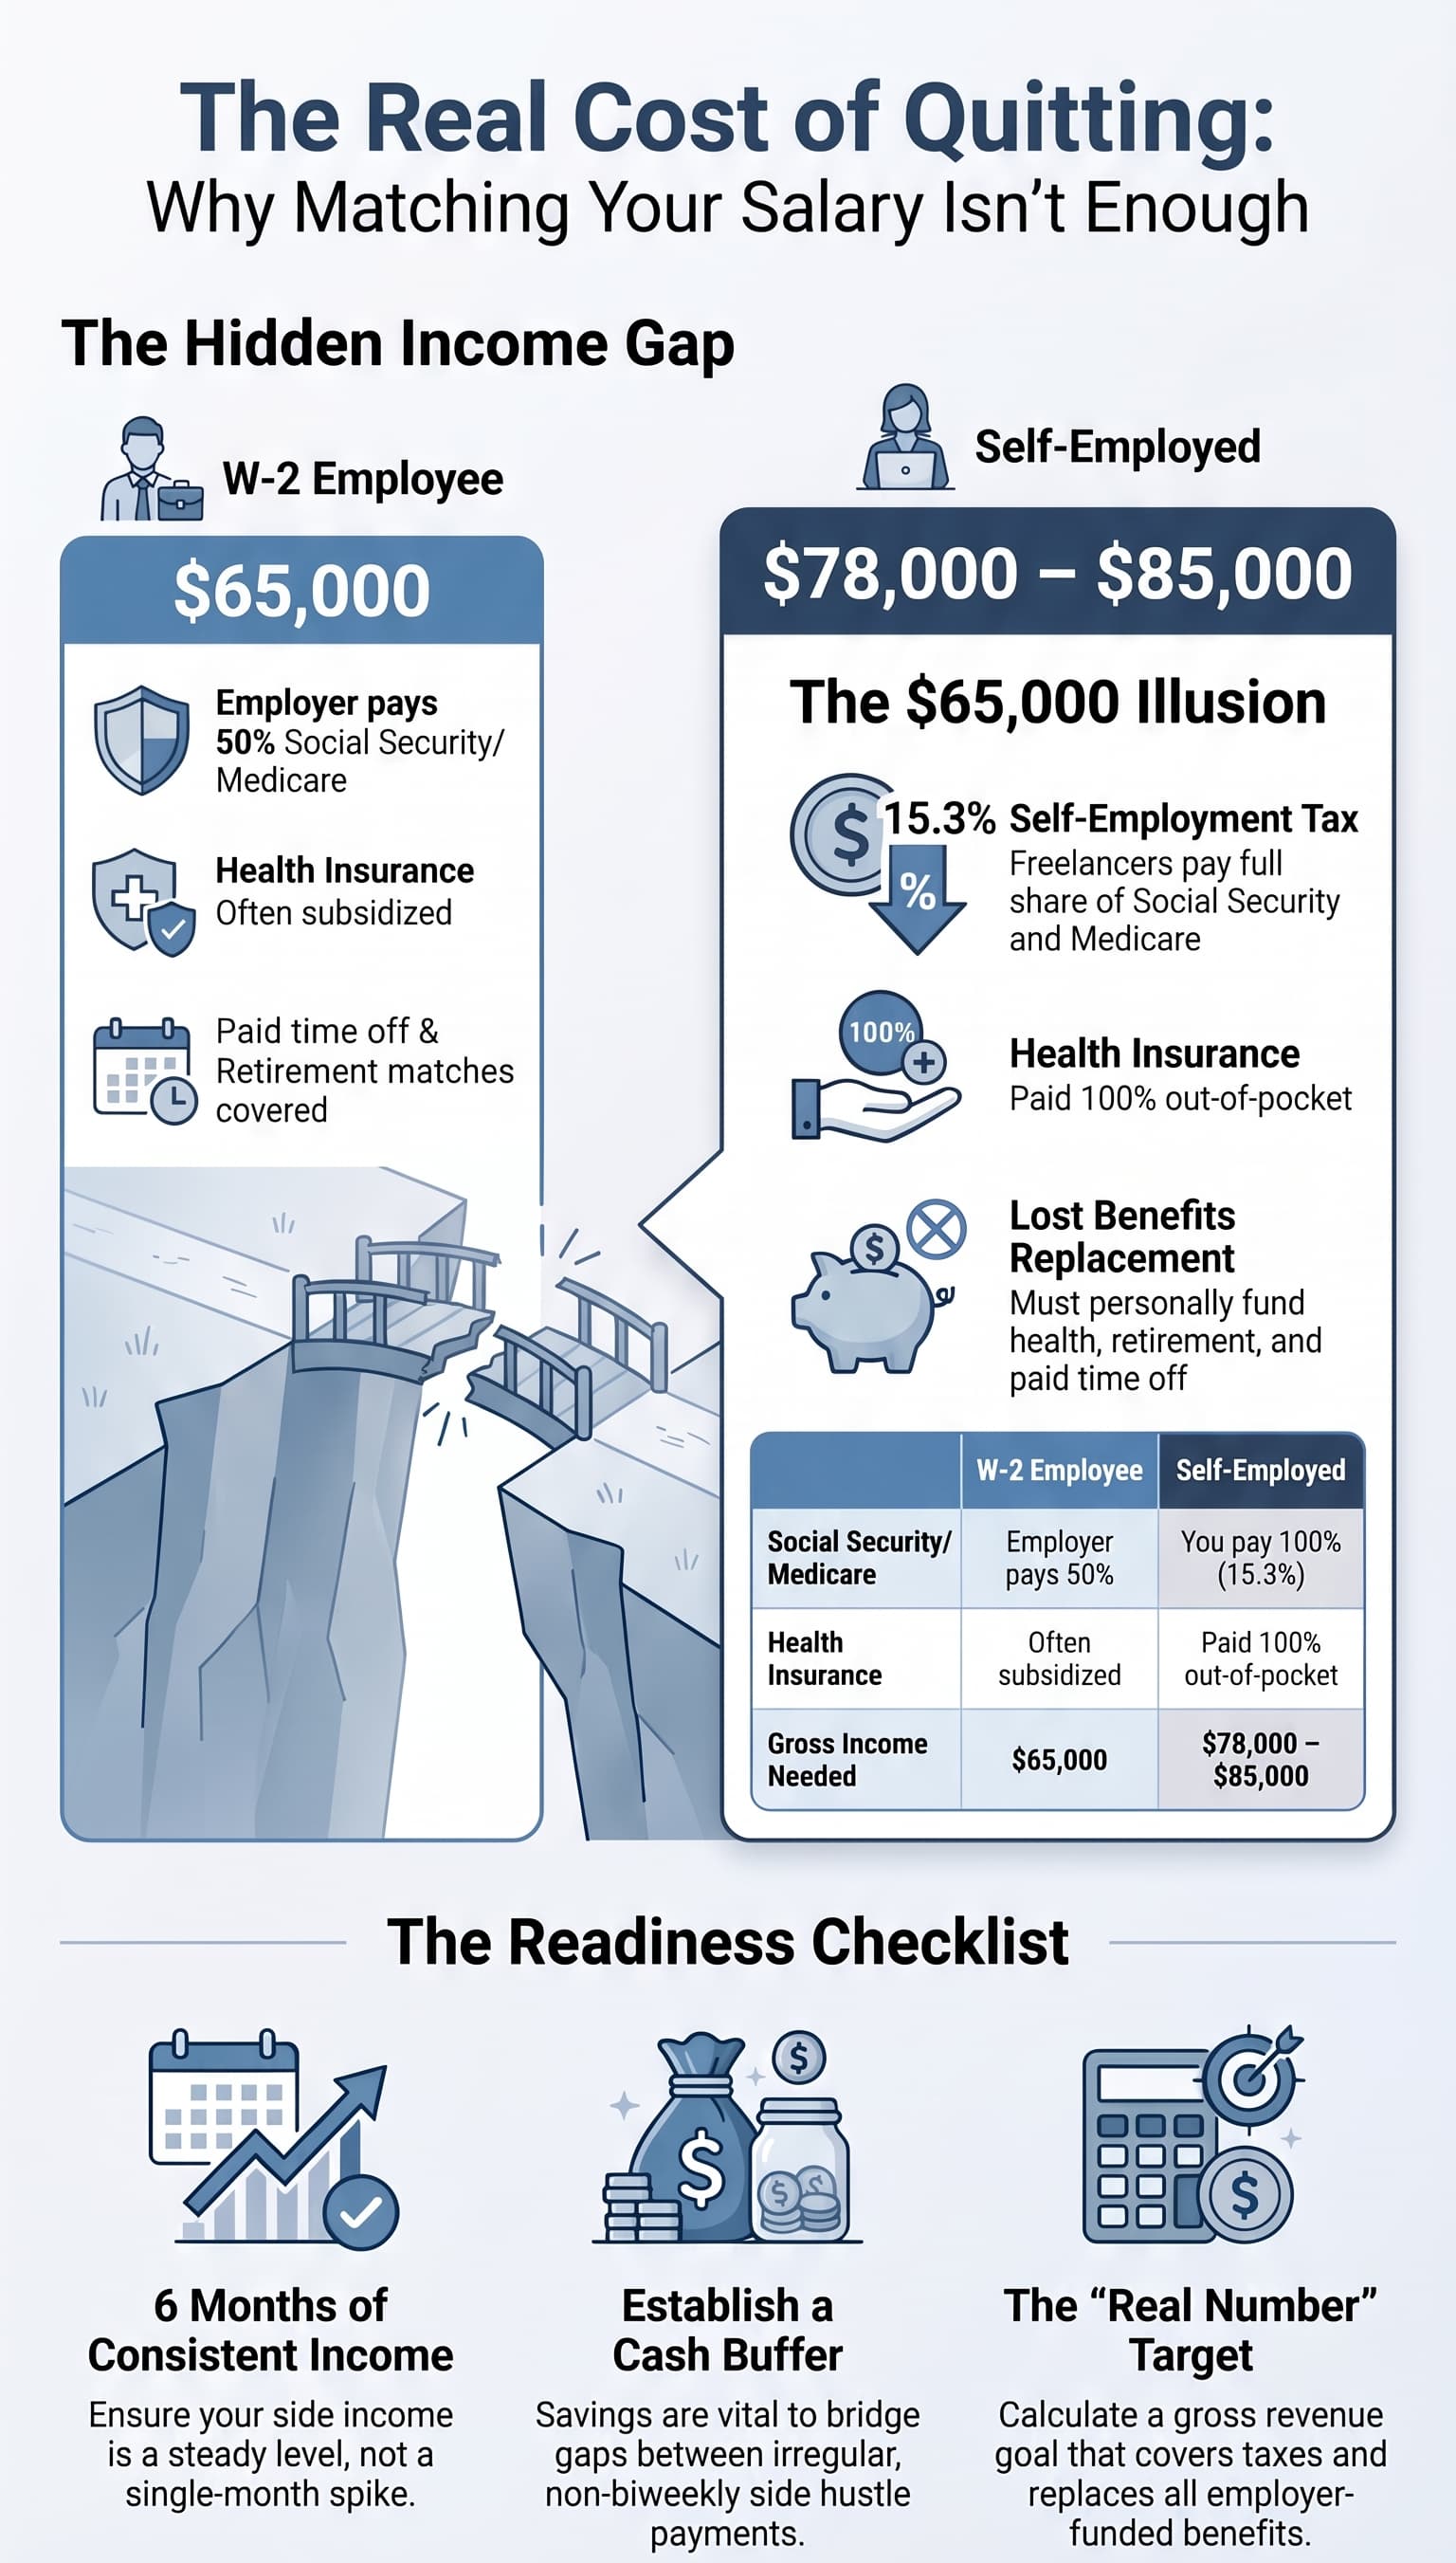
The gap the salary number hides
A W-2 salary of $65,000 comes with the employer already covering half of Social Security and Medicare, and often health insurance, some retirement match, and paid time off on top. Self-employment income has none of that built in — self-employment tax alone is 15.3%, paid entirely by the earner, and every benefit that came bundled with the job now has to be bought separately or gone without.
Replacing a $65,000 salary with self-employment income that nets the same take-home, after self-employment tax and after buying comparable health coverage, commonly takes somewhere in the range of $78,000–$85,000 of gross side-hustle revenue — the exact number depends heavily on the individual's tax bracket, state, and what benefits they're replacing, but the direction is always the same: gross side income has to be meaningfully higher than the salary it's replacing, not equal to it.
Why the timeline matters as much as the number
Side-hustle income is rarely a straight line. A driver, a seller, a consultant building a client base typically sees income that varies month to month well past the point where it first crosses a "matches my salary" threshold on paper. Quitting the moment a good month happens to clear the number, without a track record of consistency, is a different decision than quitting after six months of the number holding steady — and the second one is the one worth taking seriously.
What actually needs to be true before quitting
- The real number, not the salary number — gross side income high enough to cover self-employment tax and replace lost benefits, not just match take-home pay
- A consistency record, not a single strong month — enough months at or above the number to know it's a level, not a spike
- A plan for benefits specifically — health insurance in particular, since it's the single biggest thing an employer typically funds that a side hustle doesn't automatically replace
- A cash buffer for the gap, since self-employment income is rarely as evenly spaced as a biweekly paycheck, even once the average is solid
Where to check your own number
The Side Hustle Quit Calculator takes your actual salary, benefits, and side-hustle income and returns the real number to hit — not the salary figure — along with what's still missing and a realistic timeline based on where the income actually stands today. If the side income itself needs a closer look at what it's really netting after mileage, platform fees, and taxes first, the Gig Worker Calculator and Side Hustle Tax Calculator work out that half of the picture.
Frequently Asked Questions
Is there a standard multiplier, like "aim for 1.3x your salary"?
Rough multipliers exist but vary a lot with your specific tax bracket, state, and the benefits you're replacing — someone with employer-covered family health insurance needs a bigger gap than someone on a spouse's plan already. A calculation using your actual numbers is worth more than a generic multiplier.
How many months of consistent income should I wait for before quitting?
There's no universal answer, but a single strong month is not evidence of a level — most people who've done this well point to somewhere in the range of 6 months to a year of the number holding steady, adjusted for how seasonal the income naturally is.
Does this change if my side hustle is highly seasonal?
Yes — a seasonal business needs the annual total to clear the real number, not any single month, and the cash-buffer point matters even more since income concentrates in fewer months than a salary would.